01 | Weekly Overview
Several developments stood outacross global financial risk markets this week.
First, credit risk moved back into focus.
In the Philippines, tightermonetary conditions are increasing attention on borrowers’ repayment capacity,delinquency and asset quality. At the same time, digital lending and BNPLcontinue to expand rapidly in Indonesia.
As credit volumes grow whilemacroeconomic conditions change, financial institutions can no longer focusonly on whether a customer has a strong credit profile at the point ofapplication.
Is the applicant really who they claim to be? | Is the application behavior legitimate? | Can the borrower continue to repay over time?
Second, fraud continues to move further upstream.
Singapore issued multiplewarnings and enforcement updates involving account takeover, malicious apps,phishing through online advertising, AI-generated impersonation and money-muleactivity.
Ad → Device → Account → Identity → Bank Account → Payment
At the same time, new risk actorsare entering the financial ecosystem. AI agents are beginning to participate inreal commercial payments, creating more complex relationships among users,businesses, agents, merchants and payment systems.
The next generation of risk management therefore needs to answernot only “Who is making the transaction?” but also “Who is acting on whosebehalf, what have they been authorized to do, and is that authorization stillvalid?”
02 | Policy & Regulation
▸ Philippines |Tighter Monetary Conditions Put Credit Quality Back in Focus
The Philippines tightenedmonetary conditions further this week. For banks and digital lenders, this ismore than a macroeconomic development.
Higher funding costs → Higher borrowing costs → Greater repayment pressure → Higher delinquency risk → Higher NPL and collection pressure
Impact: The key question for the Philippine market is no longer simply whether lending continues to grow. Financial institutions should increasingly monitor whether credit growth and asset quality begin to diverge.
Source: Bangko Sentral ngPilipinas — Monetary Board raises Target RRP Rate by 50 basis points (21 Oct2026)
▸ Malaysia | AMLOversight Is Moving Toward Business Entities and Beneficial Ownership
Malaysia continues to strengthenits focus on the role of companies, trusts and professional service providersin cross-border financial crime. A notable development is the growing concernaround corporate mule accounts.
Criminal networks can uselegitimate-looking business entities, complex corporate structures andintermediaries to obscure beneficial ownership and the true source ordestination of funds.
Impact: AML is expanding from Individual Customer + Transaction Monitoring toward Business Entity + UBO + Corporate Relationships + Professional Intermediaries + Fund Flows. KYB increasingly needs to become a form of continuous business risk monitoring.
▸ Thailand | ScamRisk Is Becoming a System-Level Financial Risk
Thailand continues to advancecross-institution anti-scam cooperation. One regulatory conclusion is becomingincreasingly clear: fraud is no longer simply an operational risk forindividual banks; it is becoming a systemic risk across the broader digital-financialecosystem.
When victims, mule accounts,banks, payment providers, telecom operators and online platforms all sit indifferent systems, no single institution has a complete view of the fraudchain.
Impact: Future fraud prevention will increasingly depend on Cross-Institution Data Sharing + Network Intelligence + Real-Time Transaction Intervention.
Source: Bank of Thailand —Bangkok Blueprint in Action: Regional Experiences and Policy Lessons forFraud-Resilient Financial Services (Oct 2026)
03 | Market & Business
▸ Indonesia |Digital Financing Keeps Expanding, Bringing Credit and Fraud Risk CloserTogether
Indonesia’s digital lending,online financing and BNPL markets continue to grow rapidly. As the marketscales, financial institutions need to answer more than “What is thiscustomer’s credit score?”
• Is the applicant’s identity genuine?
• Is there evidence of multiple or coordinatedapplications?
• Are income and employment documents credible?
• Are multiple applications linked to the samedevice?
• Has repayment capacity changed?
Business Implication: A more complete digital-lending risk framework increasingly looks like Identity + Application Fraud + Credit Risk + Decisioning rather than two isolated systems for fraud and credit.
Source: Otoritas Jasa Keuangan(OJK) — OJK Mengajar 2026: Opportunities and Risks in Digital Financing (Oct2026)
▸ Asia-Pacific |Credit Is Still Growing, but Asset Quality Deserves More Attention
As financing conditions changeacross parts of Asia-Pacific, risk management is beginning to shift from purecredit expansion toward the quality of growth.
• Industry concentration
• Borrower leverage
• Asset-price changes
• Macroeconomic pressure
• Post-loan behavioral deterioration
Business Implication: Credit risk is evolving from an application-stage scoring problem into a full-lifecycle risk management problem.
Source: International MonetaryFund — Regional Economic Outlook: Asia and Pacific, October 2026
04 | Fraud & Risk
▸ Singapore |Malicious Advertising Is Becoming an Upstream Fraud Entry Point
Singapore has continued to warnusers about scams that use social-media advertisements to induce users toinstall malicious applications. Attackers may disguise these apps as legitimateservices, promotions or activities before attempting to obtain devicepermissions, credentials or payment information.
Ad → Malicious App → Device Control → Impersonation → Bank Account → Payment
Trend: Device risk is becoming an increasingly important upstream signal in financial fraud prevention.
Source: Singapore Police Force —Police Advisory on Malware from Social Media Advertisements Resulting in Nearly$1 Million in Losses (20 Oct 2026)
▸ Singapore |Account Takeover Exploits Existing Social Trust
Instead of creating a new fakeaccount, fraudsters compromise a real user’s WhatsApp account and then contactfamily members, friends or colleagues to request money. This is more convincingthan a newly created fake profile because the attacker inherits the victim’sreal social relationships.
Trend: Account security can no longer answer only “Is this a real account?” It must also answer “Is the person controlling this account still the legitimate user?”
Source: Singapore Police Force —Police Advisory on Social Media Impersonation Scams Involving CompromisedWhatsApp Accounts (21 Oct 2026)
▸ Singapore |Money Mules Remain Core Infrastructure for Scam Networks
Recent enforcement actions inSingapore continue to highlight the importance of money-mule networks in fraudoperations. Authorities are also extending enforcement beyond individual casesby restricting access to banking and telecommunications services for certainmule-related actors.
Trend: Anti-scam enforcement is moving from detecting a suspicious transaction toward identifying and disrupting the infrastructure that allows scam networks to operate repeatedly.
Source: Singapore Police Force —Police Investigate 277 Scammers and Money Mules in Islandwide EnforcementOperation (22 Oct 2026)
▸ Mexico |Financial Institutions Themselves Are Becoming Targets of IdentityImpersonation
Recent cases in Mexico showfraudsters impersonating financial institutions by misusing company names,logos and corporate information through fake apps and messaging channels. Theidentity being abused is no longer simply an individual identity; it is OrganizationIdentity / Brand Identity.
Trend: The scope of digital identity protection is expanding from customers to Individuals + Businesses + Financial Institutions + Digital Service Channels.
Source: CONDUSEF / Gobierno deMexico — Alert on Possible Identity Impersonation of Kapital Mexico GrupoFinanciero (23 Oct 2026)
▸ AI-GeneratedIdentity | Generative AI Is Replicating Institutional Trust
Fraudsters are increasingly usingAI-generated images or personas that appear to represent police officers,regulators or other trusted authorities. Previously, deepfake risk focusedmainly on “Is this person real?” The new question is “Does this person reallyrepresent the institution they claim to represent?”
Trend: Personal identity trust and institutional trust are becoming increasingly interconnected.
Source: Singapore Police Force —Police Advisory on Fake Advertisements of AI-Generated Police OfficersPromoting Scam Recovery Services (23 Oct 2026)
05 | Technology & Innovation
▸ Visa | AIAgents Are Entering Real B2B Payment Flows
AI agents are moving beyond demosand into real payment environments. Visa and its partners have begun testingscenarios in which AI agents execute approved B2B payments on behalf ofbusinesses.
• Who is the agent?
• Who does it represent?
• Who authorized it?
• How much can it spend?
• What can it purchase?
• When does the authorization expire?
What to Watch: The next generation of agentic-payment risk infrastructure will need to combine Agent Identity + Agent Authorization + Transaction Context.
Source: Visa — Visa, BILL andBilltrust Launch First Live Pilot for Trusted AI Agent Payments Between Buyerand Supplier Platforms (20 Oct 2026)
▸ Mastercard |Machines Are Beginning to Pay Other Machines
A new class of use case isemerging in which businesses assign an AI agent a task and a budget, and theagent independently selects digital services and completes multiple paymentswhile carrying out the task.
Traditional payment: User Click → Single Transaction | Emerging agentic payment: Agent Executes Task → Selects Service Providers → Completes Multiple Transactions
What to Watch: Future transaction risk models will need to understand not only amount and merchant, but also Task + Budget + Agent Identity + Authorization Scope + Transaction Context.
Source: Mastercard — WhatHappens When AI Agents Start Paying Each Other? Watch Mastercard Agent Pay forMachines in Action (20 Oct 2026)
▸ Stablecoins |On-Chain Transparency Does Not Equal Transaction Trust
As stablecoins move further intoreal payment flows, payment networks are beginning to combine traditional fraudintelligence with blockchain analytics. Even when fund movements are visibleon-chain, the transaction itself may still be fraudulent or high risk.
On-Chain Fund Flows + Off-Chain Identity + Counterparty Risk + Behavioral Signals + Payment Context
What to Watch: Digital-asset risk is becoming increasingly integrated with traditional Fraud + AML + Payment Risk Management.
Source: Mastercard — MastercardIntroduces Risk Intelligence to Enable More Secure Stablecoin Payments (19 Oct2026)
▸ DigitalIdentity | As National Digital Identity Matures, Risk Control Moves BeyondInitial Verification
As more countries developnational digital-identity infrastructure, the cost of confirming a person’sbasic identity may gradually decline. But this does not eliminate risk.
• Is the device trustworthy?
• Is the account still controlled by the originaluser?
• Has behavior changed?
• Does the transaction reflect the user’s trueintent?
What to Watch: As digital identity infrastructure matures, the commercial value of risk management will increasingly shift from One-Time Identity Verification toward Continuous Identity Trust.
Source: Vietnam Ministry ofPublic Security — Project 06 / VNeID implementation progress update (23 Oct2026)
06 | Priority Markets
▸ Philippines |Credit Conditions + Asset Quality
Tighter monetary conditions meanbanks and digital lenders need to pay closer attention to how higher fundingcosts affect borrower affordability and asset quality.
The key question is shifting from “Is credit still growing?” to“Can credit quality remain resilient as conditions tighten?”
Source: Bangko Sentral ngPilipinas — Monetary Board raises Target RRP Rate by 50 basis points (21 Oct2026)
▸ Indonesia |Digital Financing + Credit/Fraud Convergence
Digital financing continues toscale rapidly. As user and account volumes rise, identity, application fraud,multiple borrowing and affordability increasingly need to be incorporated intoone decisioning framework.
Digital lending risk is moving from Credit Score toward Credit +Fraud joint assessment.
Source: Otoritas Jasa Keuangan(OJK) — OJK Mengajar 2026: Opportunities and Risks in Digital Financing (Oct2026)
▸ Singapore | ATO+ Device Risk + Money Mules
Singapore continues to reportaccount takeover, malicious apps, AI-enabled impersonation and money-muleactivity. These risks may look different, but increasingly span the same chain:Platform → Device → Account → Identity → Bank Account → Payment.
Single-point fraud rules are becoming less capable of explainingthe full attack path.
Source: Singapore Police Force —Scam, account-takeover and malware advisories, 20–23 Oct 2026
▸ Malaysia |Corporate Mules + AML/KYB
Corporate mule accounts andcomplex business structures are becoming more important AML risk objects.
AML is expanding from individual-account monitoring towardbusiness entities, beneficial ownership and corporate networks.
07 | Regional Data
IDR 106.94 Trillion | Indonesia
As of August 2026, outstandingonline-lending balances reached approximately IDR 106.94 trillion, up 22.07%year on year.
What it signals: As digital-credit volumes continue to expand, institutions need stronger controls across onboarding, in-loan monitoring and post-loan risk management.
Source: Otoritas Jasa Keuangan(OJK) — Digital financing data for August 2026
36.57% | Indonesia
BNPL-related financing continuedto record strong year-on-year growth.
What it signals: Rapid digital-credit expansion increases the importance of credit risk, application fraud and consumer-debt management at the same time.
Source: Otoritas Jasa Keuangan(OJK) — BNPL financing data for August 2026
SGD 6.1 Million | Singapore
A recent enforcement operationinvolved 277 individuals suspected of scam or money-mule activity, linked tomore than 883 scam cases and approximately SGD 6.1 million in reported victimlosses.
What it signals: Money-mule accounts remain critical infrastructure for scam-fund movement, making account-network and fund-flow analysis increasingly important.
Source: Singapore Police Force —Police Investigate 277 Scammers and Money Mules in Islandwide EnforcementOperation (22 Oct 2026)
SGD 989,000 | Singapore
Scams involving maliciousapplications have resulted in significant reported losses.
What it signals: Device risk is moving from a secondary signal to an important upstream component of payment-fraud detection.
Source: Singapore Police Force —Police Advisory on Malware from Social Media Advertisements Resulting in Nearly$1 Million in Losses (20 Oct 2026)
36% | Thailand
Digital-financial fraud lossesdeclined significantly year on year.
What it signals: Cross-institution risk sharing and transaction intervention are beginning to influence actual fraud-loss outcomes.
Source: Bank of Thailand —Bangkok Blueprint in Action (Oct 2026)
08 | TrustDecision Insights
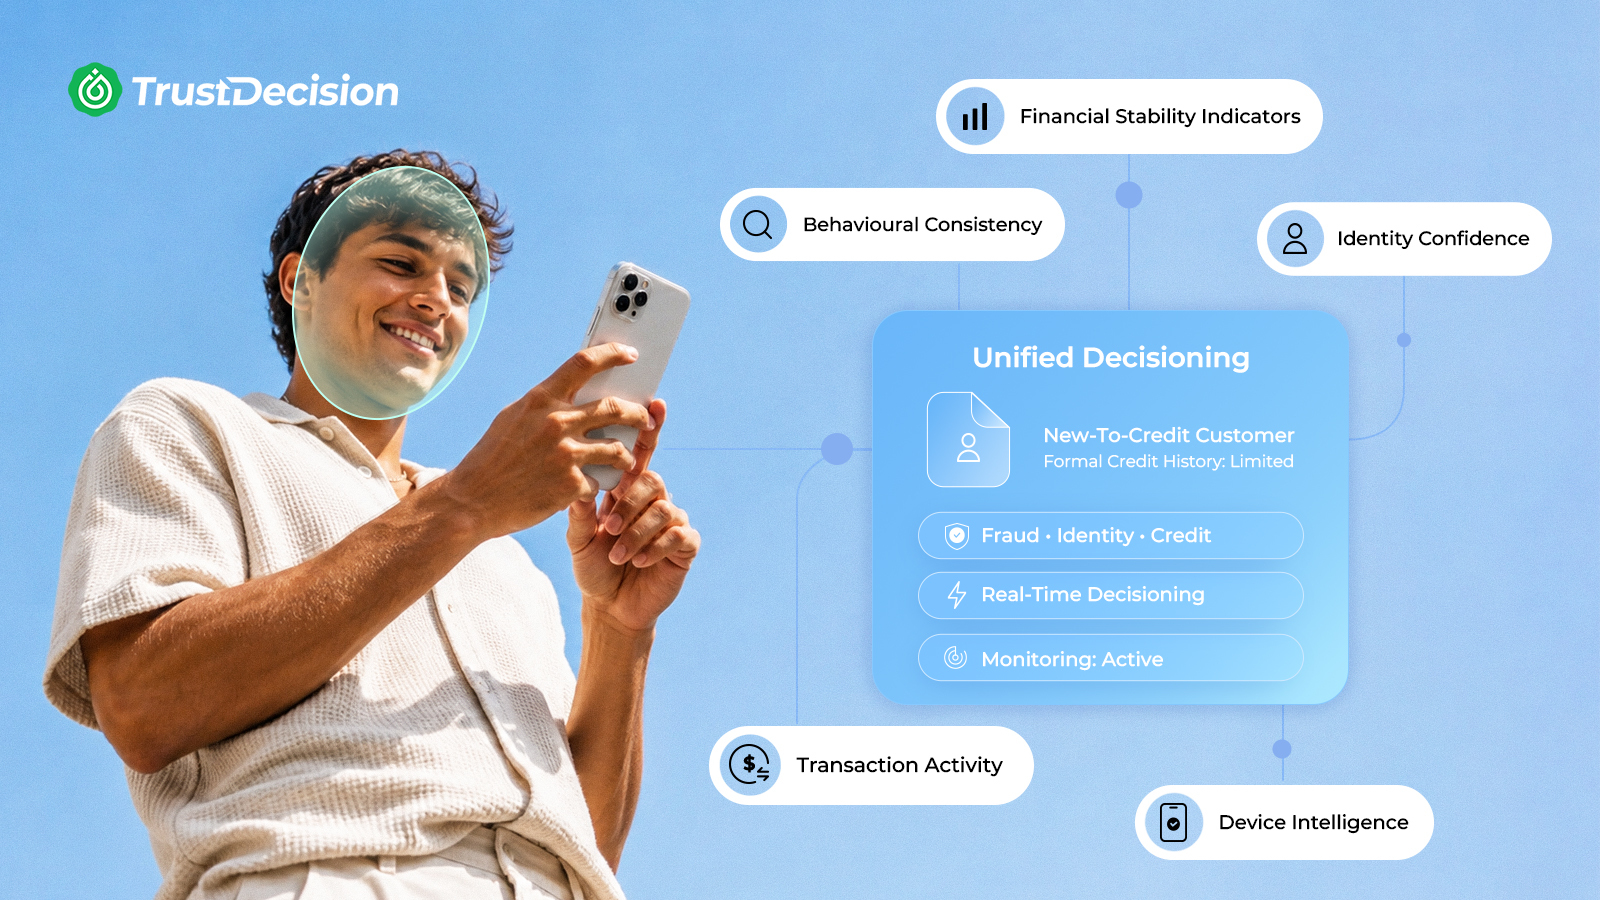
Insight 1 |Credit Risk Needs to Evolve from Credit Scoring to Credit Lifecycle Management
The Philippines and Indonesiarepresent two different market environments this week. One is facing tightercredit conditions; the other continues to experience rapid digital-financinggrowth. Yet both point to the same conclusion: a credit score calculated atapplication is no longer sufficient to manage the full credit-risk lifecycle.
Identity → Application Fraud → Credit Scoring → Decisioning → Limit Management → Behavioral Scoring → Early Warning → Collection
Fraud and credit should remain distinct risk disciplines, butthey should not operate in isolation.
Insight 2 |Identity Is Expanding from Human to Business and Agent
Several developments this weekare redefining what “identity” means. Financial-brand impersonation is anOrganization Identity issue. Corporate mule accounts are a Business Identityissue. AI agents making payments introduce Agent Identity.
Who are you? → Who are you acting for? → What are you authorized to do?
Identity Intelligence is expanding from Human Identity towardHuman + Business + Agent Identity.
Insight 3 |Fraud Is Moving from Transaction Risk to Risk-Chain Analysis
Recent cases in Singaporedemonstrate that fraud often begins long before the transaction itself. If afinancial institution only assesses risk at the final payment step, manyupstream signals have already been lost.
Ad → App → Device → Account → Identity → Payment
The next generation of fraud prevention therefore needs toconnect Platform + Device + Identity + Account + Transaction.
Insight 4 |What AML and Fraud May Ultimately Share Is Not the Same Rulebook, but the SameNetwork View
Corporate mules, cross-bankmoney-mule networks and digital-asset fund flows all share one problem: nosingle institution can see the entire relationship network.
Entity Relationships + Account Networks + Fund Flows + Investigation Context
The most important shared capability across Fraud, AML andInvestigation may therefore not be a common set of rules, but a shared networkview.
Three Actions for Financial Institutions
01 | Bring Fraud Signals into Credit Decisioning
Review whether the currentdigital-lending workflow still looks like KYC → Credit Score → Approve. Astronger approach should also include Identity Consistency + Device Linkage +Multiple Applications + Document Authenticity + Abnormal Application Behavior.
02 | Move from One-Time Verification to Continuous Trust
KYC, KYB and Credit Scoring alldescribe risk at a single point in time. Risk management increasingly needs tocontinuously evaluate device changes, account-control changes,credit-performance deterioration, business-transaction changes and agentauthorization status.
03 | Build Agent Identity and Authorization Frameworks Early
Organizations exploring AI agentsfor ordering, payments, customer service or financial operations should definein advance who the agent is, who it represents, what it can do, how muchauthority it has, how long that authority lasts, which actions require humanconfirmation, and how actions are logged and audited.
The more autonomous the agent becomes, the more importantauthorization control becomes.
Weekly Summary
One phrase best captures thisweek’s developments:
Continuous Trust
Digital lending requiresinstitutions to continuously assess whether customers can still repay. Accounttakeover requires continuous verification that an account is still controlledby its legitimate owner. Corporate mule risk requires continuous assessment ofwhether a business remains trustworthy. AI-agent payments require continuousconfirmation that an agent is still operating within its authorized scope.
“Was it legitimate when we first verified it?” → “Can we still trust it now?”
The next generation of financial risk infrastructure willincreasingly combine Real-Time Risk Assessment + Network Intelligence +Continuous Identity and Credit Monitoring + Pre-Transaction Intervention +Investigation and Response.
Monitoring Scope
This issue covers developmentsfrom October 19–25, 2026, using the updated monitoring framework acrossIdentity, Fraud, Credit, AML/KYB, Payment/Chargeback and AI/Agent risk themes.
Source note: Official or primary sources are retainedunder each news item and key data point for traceability.